Old tax regime slabs for 2026-27
You can still choose the old regime, which keeps deductions such as 80C (up to ₹1.5 lakh), 80D, HRA, LTA and home-loan interest. Its slabs have not changed for several years.
| Taxable income | Below 60 | 60 to 79 | 80 and above |
|---|
| Up to ₹2,50,000 | Nil | Nil | Nil |
| ₹2,50,001 – ₹3,00,000 | 5% | Nil | Nil |
| ₹3,00,001 – ₹5,00,000 | 5% | 5% | Nil |
| ₹5,00,001 – ₹10,00,000 | 20% | 20% | 20% |
| Above ₹10,00,000 | 30% | 30% | 30% |
- Standard deduction for salaried employees: ₹50,000.
- Rebate of up to ₹12,500 if taxable income is up to ₹5 lakh.
- 4% cess applies as in the new regime.
New or old regime: which is better?
For most salaried employees, the new regime now gives lower tax, because its slabs are wider and the rebate covers income up to ₹12 lakh. The old regime can still work out cheaper if you claim large deductions, typically a combination of full 80C, HRA on high rent, home-loan interest and 80D. The only reliable way to decide is to calculate both with your actual figures; the calculator does this side by side.
Salaried employees choose a regime with their employer at the start of the year for TDS purposes, and can switch when filing their return. People with business income can switch back to the old regime only once.
Surcharge on high incomes
| Total income | Surcharge (new regime) | Surcharge (old regime) |
|---|
| ₹50 lakh – ₹1 crore | 10% | 10% |
| ₹1 crore – ₹2 crore | 15% | 15% |
| ₹2 crore – ₹5 crore | 25% | 25% |
| Above ₹5 crore | 25% | 37% |
Marginal relief also applies at each surcharge threshold.
What changed under the Income-tax Act, 2025
The Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026. The slabs above carried over unchanged, but some names changed:
- “Tax year” replaces “previous year” and “assessment year”. Income earned from 1 April 2026 to 31 March 2027 is tax year 2026-27.
- TDS on salary is now under section 392 (earlier section 192).
- Form 16, the annual TDS certificate from your employer, is now Form 130, and the quarterly salary TDS return Form 24Q is now Form 138. Certificates and returns for 2025-26 still use the old names.
For employers: TDS on salary
Employers must estimate each employee’s tax for the year under the regime the employee chose, and deduct it evenly from monthly salary. Deposit TDS by the 7th of the following month (30 April for March), file the quarterly return on Form 138, and give employees Form 130 by 15 June after the year ends. Payroll software such as HivePayroll’s TDS management does the monthly calculation, collects investment declarations and produces the returns; it is free for up to 10 employees.
Earlier years’ slabs (for reference)
| New regime | FY 2023-24 | FY 2024-25 | FY 2025-26 and 2026-27 |
|---|
| Nil | up to ₹3 lakh | up to ₹3 lakh | up to ₹4 lakh |
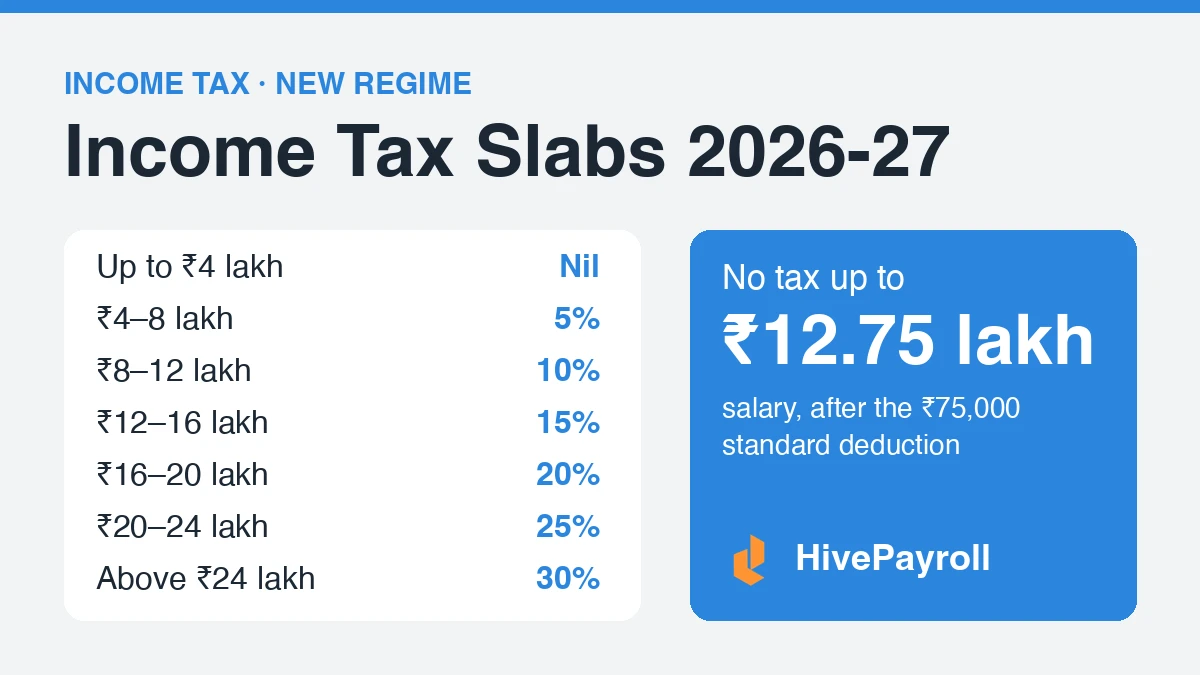
| 5% | ₹3–6 lakh | ₹3–7 lakh | ₹4–8 lakh |
| 10% | ₹6–9 lakh | ₹7–10 lakh | ₹8–12 lakh |
| 15% | ₹9–12 lakh | ₹10–12 lakh | ₹12–16 lakh |
| 20% | ₹12–15 lakh | ₹12–15 lakh | ₹16–20 lakh |
| 25% | – | – | ₹20–24 lakh |
| 30% | above ₹15 lakh | above ₹15 lakh | above ₹24 lakh |
| Standard deduction | ₹50,000 | ₹75,000 | ₹75,000 |
| Rebate: no tax up to | ₹7 lakh | ₹7 lakh | ₹12 lakh |
Frequently asked questions
What is the income tax limit for 2026-27?
Under the new regime, no tax is payable on taxable income up to ₹12 lakh because of the rebate, or up to ₹12.75 lakh of salary after the ₹75,000 standard deduction. The basic exemption limit itself is ₹4 lakh.
Did Budget 2026 change the income tax slabs?
No. The slabs, standard deduction and rebate for 2026-27 are the same as for 2025-26.
Is the new tax regime compulsory?
No. It is the default, but individuals can choose the old regime. Salaried employees inform their employer for TDS and can change their choice when filing the return.
What is the tax on a salary of ₹15 lakh?
Under the new regime, taxable income is ₹14,25,000. Tax is ₹20,000 + ₹40,000 + ₹33,750 (15% of ₹2,25,000) = ₹93,750, plus 4% cess of ₹3,750, so ₹97,500 for the year.
Is Form 16 still issued?
For 2025-26, yes, as Form 16. From tax year 2026-27, the same certificate is called Form 130.
This page reflects the Income-tax Act, 2025 and Budget 2026 as of 26 September 2026. It is general information, not tax advice; for complex cases, consult a chartered accountant.